
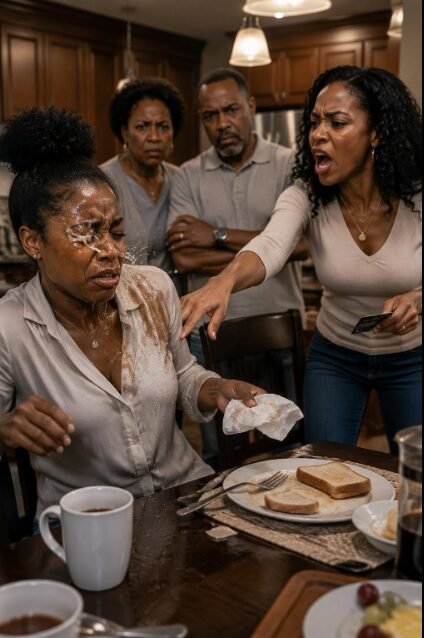
The heat from the coffee on my skin had finally subsided into a dull, throbbing ache, but the sting of the notification on my screen burned far deeper. I sat inside my quiet car in the parking lot of my apartment building, staring at the forensic log on my laptop. As a senior fraud investigator, I spent my life looking at raw data—impersonal numbers, IP addresses, and device signatures. Seeing my own mother’s device name tagged as the authorization hub for a fraudulent six-thousand-dollar transaction felt like a physical blow to the chest.
I took a deep breath, forcing my professional training to override the rising tide of personal heartbreak. In my world, emotion was noise; evidence was signal. I opened my specialized bank terminal, authenticating my access with a security token. If my mother’s iPad had been used to attach my primary credit card to a third-party digital wallet, it wasn’t a sudden impulse. Adding a high-tier credit card to a digital wallet requires two-factor authentication, usually sent via SMS or email confirmation.
My hands flew across the keyboard as I pulled the historical log for my personal cell account. Two weeks ago, while visiting my parents for Sunday dinner, I had left my phone on the kitchen counter for twenty minutes while helping my father carry groceries from the garage. Right there in the carrier logs, recorded at 6:42 p.m. on that exact Sunday, was an incoming verification code from my bank, followed immediately by an outgoing deletion command.
They hadn’t just thrown hot coffee at me this morning out of sudden frustration over a declined card. They had built a back door into my financial life weeks ago, assuming I was too naive or too devoted to notice. Beatrice hadn’t just reached into my purse to grab a physical piece of plastic; she was using a pre-authorized digital clone of my card that my mother had helped her set up.
My mother’s words from breakfast echoed back to me with a sickening new context: Family is supposed to help family. To her, “helping” meant quietly liquidating my independence to fuel my sister’s insatiable vanity. They viewed my hard-earned savings not as my personal security net, but as a shared family vault that I was selfishly holding hostage.
I opened a fresh case file on my secure drive, titling it with standard legal nomenclature rather than names: Target Alpha (Beatrice), Target Beta (Mother). I attached the screenshot of the declined $6,240 transaction, the device registry showing the iPad’s MAC address, and the cellular verification logs. Then, I added the high-resolution photograph I had taken of the red, blistered scald marks on my right cheek.
As a fraud investigator, I knew that building a bulletproof case required establishing a clear pattern of criminal intent. A single disputed transaction could be blamed on a “misunderstanding” or a “family mix-up.” But a series of deliberate, unauthorized financial maneuvers executed over time across state lines constituted systemic fraud.
My phone chimed on the console. It was a text message from my mother. Lauren, your sister is in tears. The venue is threatening to give her date away. You need to call the bank and tell them the transaction was authorized. Stop acting so bitter over a spilled cup of coffee.
I stared at the message, feeling the last remaining fragment of filial loyalty turn to cold ash. I didn’t reply. Instead, I opened my investigative toolkit and initiated a full audit of every joint account, co-signed document, and shared utility line connected to my name over the last five years.
Within minutes, the screen began to flash with red flags, each one revealing that the morning’s discovery was only the tip of an iceberg.
Turn to the next page to see what Lauren discovered in the bank archives.
